by Sara S
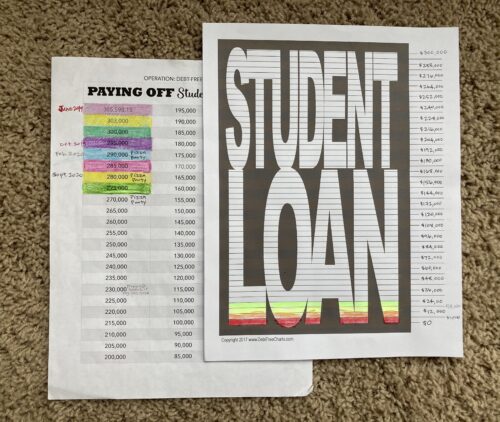
Time for another debt update. There’s one thing that’s been on my mind since our fourteenth anniversary a few weeks ago: from our wedding in 2006 to now, we’ve only known one year of being debt free. ONE year.
During our first honeymoon months, we were paying off the student loans from my undergrad. We got those done quick, so then we had one free year of bliss where I was working full-time and he was a student working part-time. We owned our old cars, had no credit card debt, and had no mortgage. We sure didn’t have much, but we were in a good place.
But then he started grad school in 2008 and that alllll went away. We took loans out that first semester, and then it went deeply downhill from there. So, so deep.
Current Numbers for Our Debt Update
So where are we now? We’ve gained some momentum since my last debt update in September. In November our debt principal got down below $275,000.
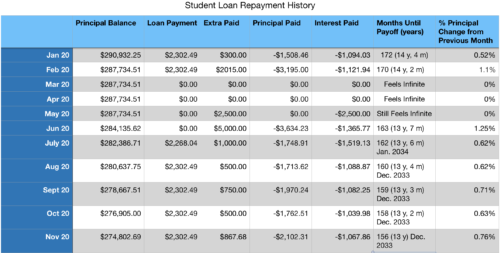
That means in 2020 so far we’ve paid off
– $17.635.28 of principal
– $11,879.83 of interest
We wanted to pay off at least $30,000 of debt principal in 2020, but I guess sometimes pandemics happen. I would love to get to $20,000 by the end of the year, but I don’t see how we can pay off $2,361.98 of principal alone this month.We’ll at least pay $500 extra, but over $2,000 is a pipe dream.
That’s only a 6% change to our principal for 2020 so far, and in 2019 we had a 12% change. Friggin’ COVID. However, for a very long time we had a 0% principal change, so I guess 6% is something. And looking back, in November of 2019, our debt principal was $294,000 and in November 2018 it was $334,810. Baby steps.
Making Extra Payments
I’ve been able to pay some extra lately thanks to a small tax refund (as a result of our business audit), an insurance rebate, and my side hustles. Unfortunately, one of my freelance jobs just ended, and it will be hard to replace. The people were great to work with, it didn’t require a lot of time, and it was really rewarding.
Fortunately, my husband will get to work at his side hustle again next week. He hasn’t done that since the beginning of the year because of the Coronavirus, so it will be nice to have that extra again.
Another additional increase comes from the Ally savings account we set up in October. We’ve already yielded $17 in interest! It’s easy to think “$17… woop-di-do!” but considering our normal savings account was giving us cents at a time, that’s an amazing increase in just two months. Why didn’t I do a high yield savings account sooner??
But I do wonder if we should just keep those yields in the Ally account so they keep accruing, or if we should put it towards our debt payments from time to time. Any thoughts?
So the gist of our December debt update is slow but steady change. Despite having 13/14 years of our marriage be debt-oriented, we are digging ourselves out of the hole. We even managed to shave off 7 months of our debt payoff timeline, even during this insane year.
So I’m hoping to end 2020 strong. Strong-ish. As strong as 2020 allows. 😉