by Adam Dawson
When I started blogging here, I would dream about the final debt payoff post, with how many stupid images I’d include with confetti and party hats, how loudly I’d celebrate our accomplishment. I considered calling up Dave Ramsey to do the debt-free scream, an idea I quickly abandoned when I remembered I’m not much of a screamer. (Which means I’ll probably never get on The Price is Right either. Too bad because I’d slay the competition on that show.) But I still thought I could throw a virtual party here and celebrate with the community that we had crossed the finish line.
T.S. Eliot wrote the depressing poem, “The Hollow Men,” with its oft-quoted, famous final stanza:
This is the way the world ends
This is the way the world ends
This is the way the world ends
Not with a bang but a whimper
Officially, it was November 15, 2013 when Emily and I set the 2-year debt payoff goal in this post, where we said we’d be debt-free by December 31, 2015. So I thought I should come back one more time to update everyone on this goal. But I’m going to be a jerk and make you suffer through some other updates before I give you the answer. (OK fine, if you want to skip the updates, scroll down to the next divider line.)
You’ll remember that we decided to relocate to Silicon Valley for a new job this summer. I predicted my loan payoff would slow down as we shifted money to pay for housing here but that my stock compensation and retirement contributions would go way up. This has turned out to be exactly true. We are living in a tuna can apartment that costs over $3000 a month and I cringe every time we pay rent. But we also spend a little less on home maintenance, and costly hobbies like woodworking and gardening have disappeared too. On the whole, however, our cost of living is way higher primarily due to rent.
Fortunately, my job is going well and my hopes for the long term financial boost are looking like they will work out well (depending on how the company does while I wait for my stock grants to vest). I saw an anonymous internet thread where tech industry employees posted their age and net worth, and I was gobsmacked by the numbers these people reported. For my age I am WAY behind these kids who come to work out here right out of school. I’m talking about 26-27 year olds who are reporting net worth numbers in the $300,000 – $800,000 range. Ridiculous. I mean, it’s anonymous and who knows how accurate any of the reports were, and maybe there is selection bias where people with lower figures don’t bother reporting them, but the takeaway for me was that we could end up doing pretty well I stick around the industry a while, even if I’m part of the geriatric division.
The thing is, Emily and I have some values that may be a little different than people who are maximizing their net worth numbers. I really like my job and company. But we’ve so far chosen for Emily to stay home with the baby. I don’t feel the obligation to put in all the extra hours and effort it might take me to advance in my job faster. And we have really started to feel like raising our growing family within close proximity to their grandparents and other family members is something we would really like. We have also realized that we feel somewhat like fish out of water in the Bay Area culture. In general it feels like people are not too friendly here, often entitled, and overly focused on technology (meaning not very interesting). While it’s ethnically diverse, it often feels like a nerd monoculture and the worst of everything you’ve heard about entitled millennial tech workers who can’t see beyond the end of their own smartphone is generally on point. Someone told me they couldn’t fathom having more than one child because private school tuition for more than one child is too expensive.
I say all that to illustrate that although I really like my job and my company, and it stands to be a financial windfall eventually, we aren’t quite sure how long we can last out here. In our desperation to get out of here, I have done a number of retirement calculations to find the lowest net worth figure I can accept at age 34, 35, 36, 37 that has a 95% chance of growing to a comfortable retirement nest egg. (I actually created a detailed spreadsheet with historical average market returns and a statistical prediction model that runs hundreds of simulations and shows me the % likelihood our investments will hit a certain threshold by age 65. Leave a comment if you’d like a copy of it for yourself.)
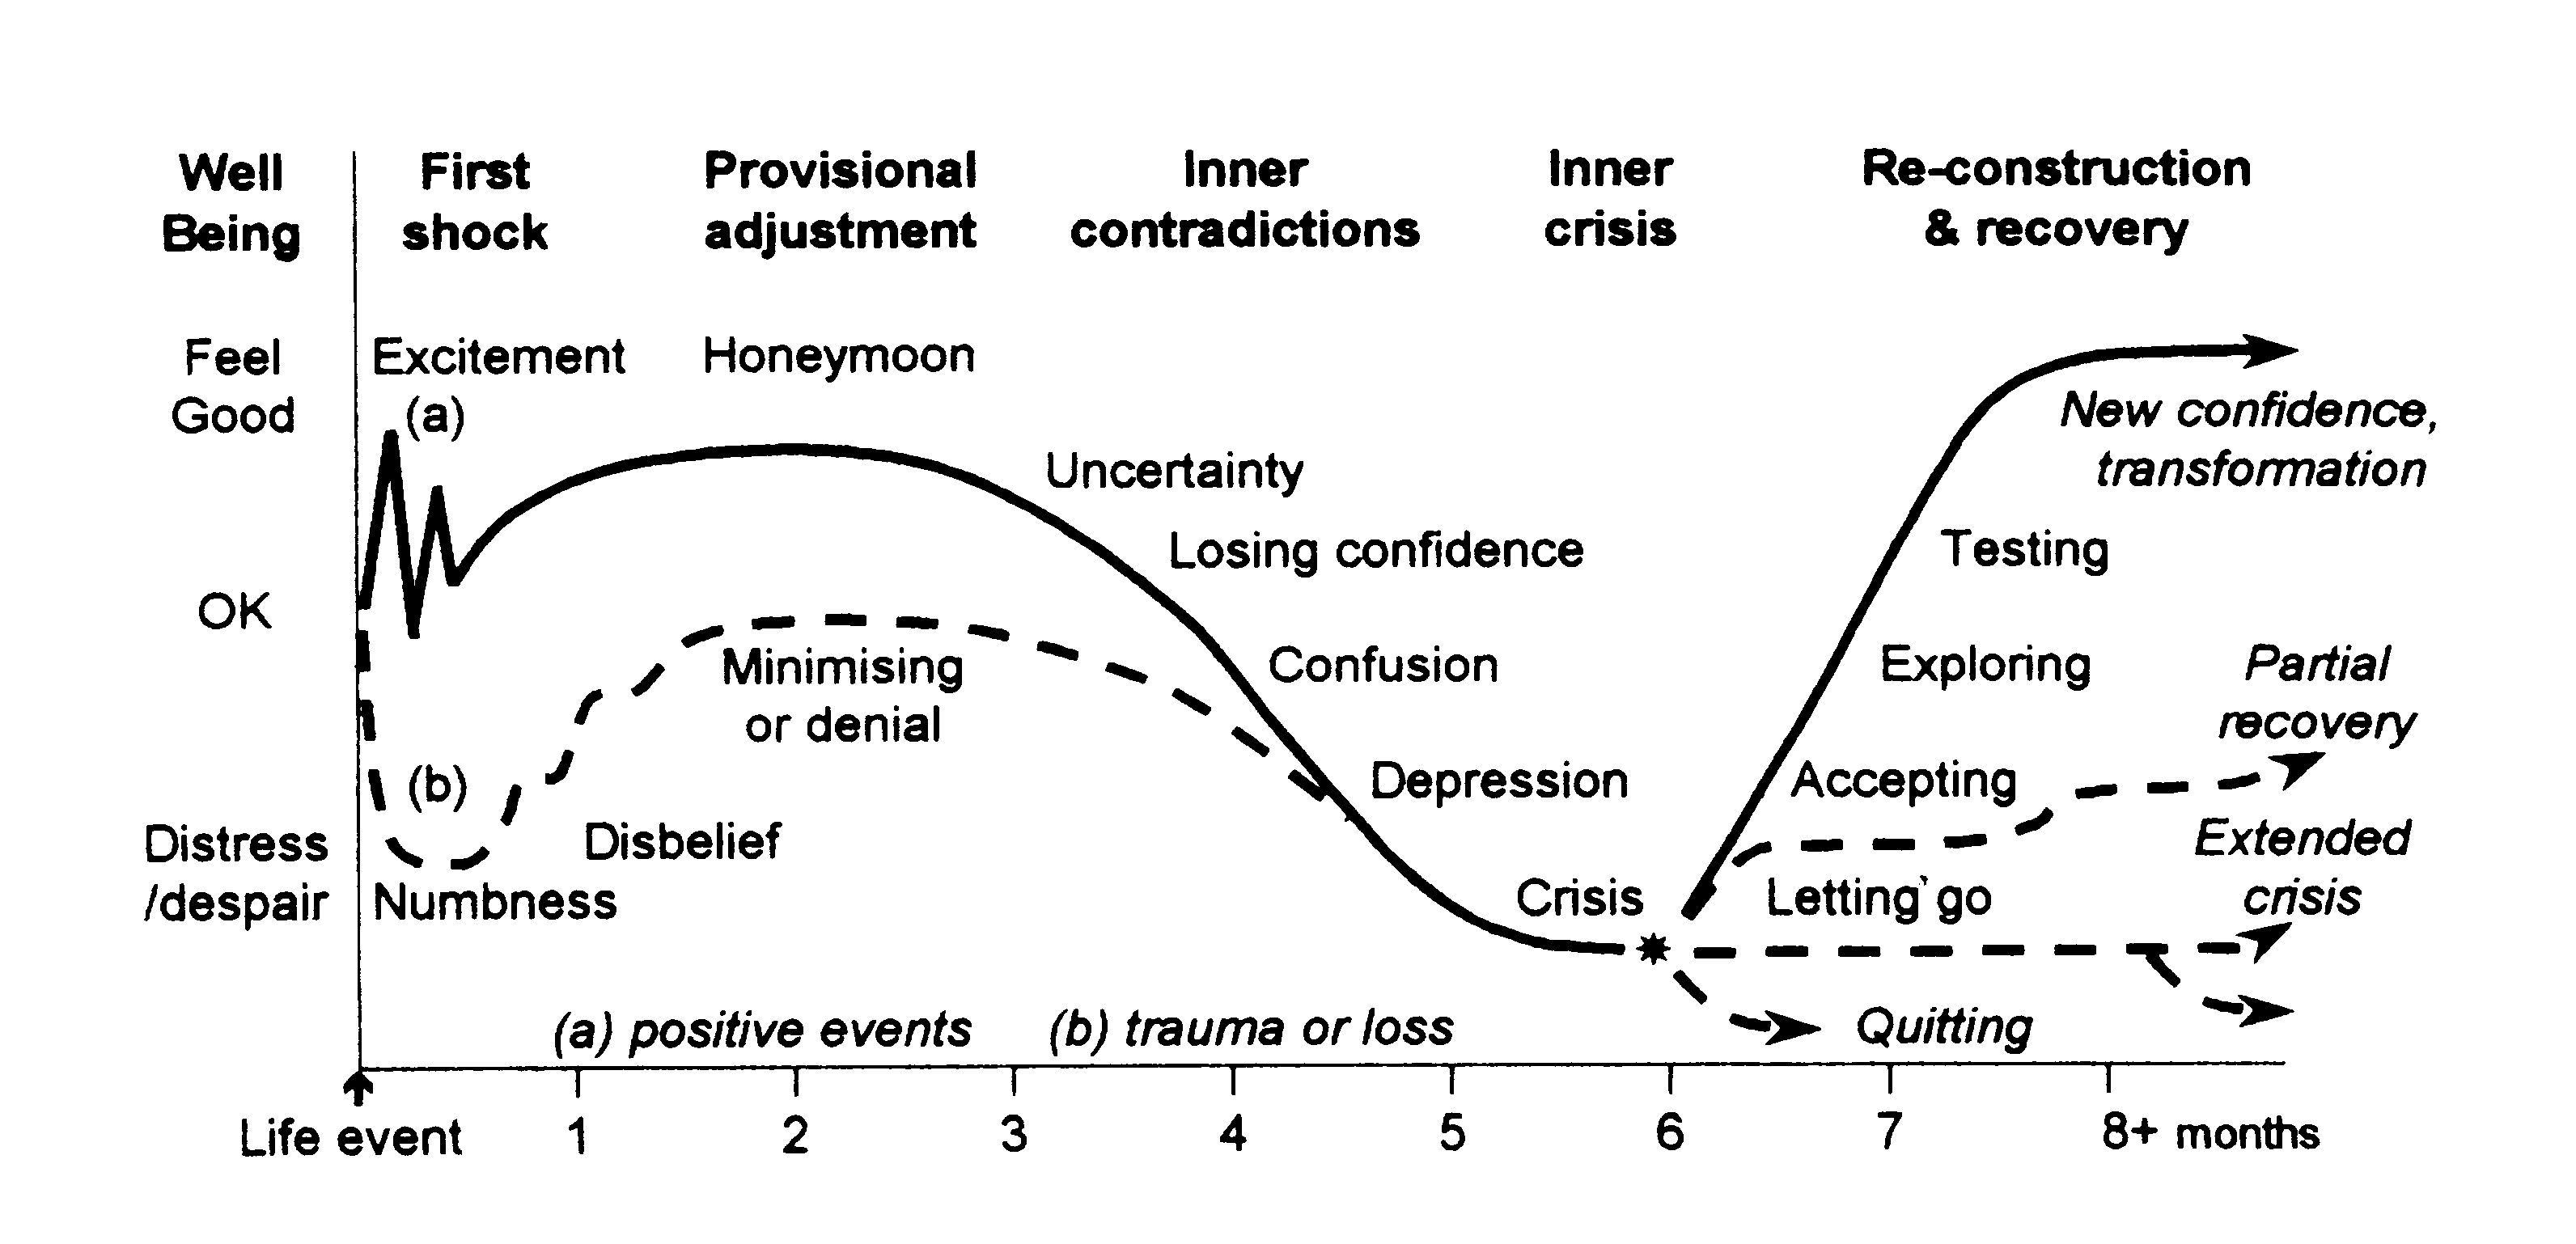
On the other hand, I also stumbled on a concept known as Transition Theory that talks about the personal cycle of career change, and realized that the initial shock of a big change like this is common and it often takes about 6 months to start climbing out of the crisis and recovering to your previous level of personal satisfaction. We just hit the 6 month point in the Bay Area and I do admit things are feeling a bit more comfortable here. So maybe by the springtime, we’ll feel a sense of renewed purpose here and get settled in.
We also told you in May about our new family addition. She is now a toddling 1 year old and doing great. Everyone says kids are expensive but so far, we’ve found that the added expenses of having her around are more than offset by the fact that we hardly go out any more. We used to spend quite a bit of money on restaurants and movies and activities with friends. Now we spend it on diapers and wipes and the occasional Amazon movie rental. I think it’s actually cheaper overall (for now), with the notable exception that we now need an extra bedroom, so maybe on the whole she really is pretty costly.
Finally, our real estate investments are finally starting to do ok. I have one property (my original house) that is a total dog but is treading water while I pay down the balance. The two other properties are doing quite well, generating about $600 and $800 per month in positive cash flow per month. I could see cashing out of the Texas house in the spring but it’s probably smarter to try to hold on for a few years while Austin real estate values continue to increase. Selling would net us maybe $60-$70k, but I think holding on for 2 more years could get that number to $100k or more.
Okay, so with all that, what is the status of our December 31, 2015 debt payoff goal?
Well, it’s good news and bad news. Good news is that we are effectively there. Meaning that we have enough money in the bank to pay off our remaining balance, although that would leave us with very little leftover. Going into January, I am getting a decent cash bonus as well as a third paycheck next month, so our balances will grow in the new year. I am also hoping for a couple thousand bucks in tax returns, but with the rental properties and all the changes this year, I have no idea what to expect.
The bad news is that the balance on my last student loan is still about $33,000 and I have been paying the minimum payment every month of $231. So we aren’t really debt-free yet. *Sad trombone* 🙁
We have been hoarding our cash for a few reasons:
- As renters we may move again soon and most places demand a 1-month deposit plus first month’s rent, meaning we shell out over $6000 to move in somewhere. We are in an apartment right now but would like to find a house we can stay in permanently until we are ready to leave the area. We are so sick of moving, but our apartment isn’t really a good fit for us.
- We are torn on whether we should try to buy a house out here. Most houses within a reasonable commuting distance are completely outside our range ($1M+ for a completely outdated 60s-era 1200 sqft shack in need of major TLC). To afford anything we’d need to move a ways away and get ready for a 1-hour commute or more. We are considering it, and if we decide to buy a house here, we will need our savings to contribute to a down payment. The housing market is white hot here, meaning it could be a good investment, and it could also be wise to get out of the renters cycle, which is also insane. (One duplex we looked at last summer for rent had a single, half-hour open house and received over 12 applications. We were not selected despite our healthy bank account and good credit. Another landlord wanted to charge us a $300 deductible on ANY repair.) At this specific time, we don’t expect to buy a house anytime soon. Ask us next week, maybe we will change our minds.
- Our cars. Our 14-year-old Lexus SUV (affectionately called Wrecks-us because of all the dents and dings) has now reached 220,000 miles. It still runs like a dream but it feels risky and has needed a good amount of repairs, so we may need to consider replacing it soon. We are completely opposed to another car payment and fine with driving a well-used car, but anything in reliable shape under 100,000 miles will still cost us close to $10,000 I’m guessing.
- Low interest rate. The remaining $33,000 loan is locked in at 2.75%. While I REALLY want to be debt-free, it’s such a low rate that it probably makes mathematical sense to keep the cash invested somewhere and pay the debt off slowly. This is not a major decision factor as I’m more apt to choose the emotional well-being of wiping out the debt, but whenever I get close to making that decision, the low interest rate rears its head and asks, “Are you suuuuure?”
So we’ve come full circle. We didn’t get the debt paid off by December 2015 like we meant to, but we did save just enough money to do so and have a bunch of equity in our Austin house we could liquidate if needed. With the cash boost in Jan-Feb timeframe, we may decide to go ahead and pull the trigger. But we may also decide to buy a house in California or may need to shell out $6k-7k to move in to a rental unit.
I don’t know if you’ll give us the credit for reaching our goal or not, but I consider this a miniature celebration. Our financial peace and well-being is at an all-time high, as-is our net worth. We have enough money to survive very comfortably. My 2016 income is projected to be very high and our net worth should grow by almost 50% next year. We constantly feel very fortunate, even lucky, to be in this position (in fact we are prone to Impostor Syndrome – feeling like we don’t really deserve this). If I can manage to keep my job for another 3-4 years we will have enough money socked away that our retirement will be close to “guaranteed,” and we could choose do any job or opportunity that just pays the bills without worrying about savings. If we choose to stay here 10 years, we’ll be millionaires and will never have to worry about money again, but we may lose our souls in the process.
I quoted Eliot above because this end to the story is much more of a whimper than the bang I expected. But it is success nonetheless. I expect this to be our final final final update unless maybe I come back to say that we sent the last student loan payment sometime. Thanks to the community here for all your support and encouragement during the process. Sorry that we couldn’t continue blogging the entire time but I’m happy we had the chance to come back and update you all. I can tell you that without our experience here and the urging of the readers, we would not have made the decision to do the 2 year payoff plan and we’d still be $60-70k in debt. So again, THANK YOU!, MERRY CHRISTMAS, HAPPY NEW YEAR!
P.S. There is the small matter of the 40-acre apple orchard I found for sale in Michigan…We’ve had the thought of putting in an offer.


