by Jeffrey Strain
Note: This is the introduction the Jim put together to introduce himself to all of you in hopes of becoming the next blogger for BAD. If you have any questions or observations for him, please leave a comment. You can find more information about this blogging position here
Hey everybody, my name is Jim, a 32 year self-employed husband and father of two. I have been on the road to get out of debt since last year. And to be honest I thought I was doing pretty well, paid off three credit cards, all my student loans, and a personal loan. This all done on about $30,000 combined income for my wife and I.
My greatest accomplishment was paying off the pain in the butt personal loan at the end of the year It just so happens to be also one of my biggest consumer mistakes I have ever made. My wife and I were just moving in together, when we got this loan for all of our furnishings. They were marked at great prices, and even had a 18 months same as cash plan. Well turns out that they didn’t make the monthly payments to equal a complete payoff in 18 months. And when month 18 came around, we got hit with all the incurred interest. Needless to say a $5,000 loan turned into $9,000.
Have you ever heard the Booker T. Jones quote, “If it wasn’t for bad luck, I wouldn’t have any luck at all,” well story of my family’s life. We don’t dwell on it, but almost all the time, things just don’t work out for us. Don’t get me wrong, there are periods of time where everything is going pretty good, but then we are hit with something we didn’t expect, or something that was totally out of our grips to control.
We have no savings, no emergency fund, no college savings, and very little for retirement funds and live month to month. At the end of last year, I had written up a game plan and that was to really snowball our debt and start building our credit scores back up to a respectful number. But as stated in the last paragraph, our luck just wouldn’t let this happen for the last few months and we ended up taking more debt on.
Let me start from the beginning of this year… First off I was totally unprepared for the winter that we have been having. We have been in the house that we rent, since End of September 2011. Before that we rented apartments. With that said, we were going through roughly 100-150 gallons of oil per month, the last two years. Well this winter, we have been going through 250-300 gallons (I honestly don.’t even know how I came up with this money). and we ran out of oil on two occasions. On both occasions we had oil coming the next day. Last week was one of those occasions, and well… Our pipes froze overnight and the radiator in our kitchen burst. Talk about an added expense, with that and the next thing I talk about about… there went our income tax return.
In the beginning of last month, my wife and I were in a car accident where we hit some black ice and went into a guard rail. The vehicle that we were driving (’04 Chevy Malibu) was deemed a total loss. I only had $1400 left to pay on it. Now I hated this car, I put just about the same amount of money fixing this beast as I did financing it. I was hoping to get another year at least out of it, then trade it in for something better. If everything would have worked out, it would have been paid off in April if not sooner, and we could have started saving for one. Well after everything was said and done, we got $2400 for the payout.
I already knew that both the wife and I had pretty bad credit (I will tell you about it in another post, if I am chosen) and I was going to start working on this, this year. As this was our only vehicle, we had to find another one. The wife and I had each a stipulation when we were out buying a vehicle. Her’s being that if I wanted another child that we get a bigger vehicle. Mine was that I wanted one that had low mileage so I would be able to pin point many things that could be wrong with it, as I do most of the car maintenance on my own. We ended up getting a ’13 Dodge Grand Caravan.
I am pleased to say that we love the van, what I can also say is that I hate the financing that we got. I hope that I can get it refinanced, if there is such a thing. But we do have sub-prime credit… and might have to take the big hit if we have to.
Well I know all of you readers are number people and want to see the numbers so here you are. The first table you might not be interested since it has to deal with my utilities and everything, but it is something I track so I am still going to put it here.
| Rent | Electric | Oil | Verizon | Auto/Renter Ins. |
|---|
| January 2014 | $600 | $105.44 | $1019.79 | $76.35 | $369.28 |
| February 2014 | $600 | $84.46 | $388.90 | $76.59 | $134.52 |
| March 2014 | $600 | $89.10 | $ | $76.54 | $118.48 |
And here is my total debt numbers as of the end of last month… Please note that there are two car amounts, that is because we still have a balance until the bank gets the check from the insurance company.
Store Card #1: $203.18 (24.99% APR)
Store Card #2: $532.55 (22.9% APR)
Credit Card #1: $3279.37 (13.99% APR)
Personal Loan: $1725.63 (15.5% APR)
Car Loan #1: $1435.92 (10.19% APR)
Car Loan #2: $17914.69 (12.99% APR)
——-
Total: $25,091.34
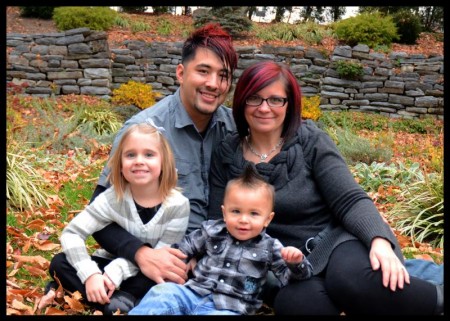
So there you have it… As of next month I will be starting from scratch, and am willing to take any and all suggestions into advisement if I am chosen. Not only will I talk about my journey to get out of debt, but I am also willing to talk about how I am trying to improve my credit and everything that is dealing with personal finance. Before heading out I also wanted to leave you with a picture of me and my family.