by Ashley
When I was a graduate student, I remember having a conversation with my mentor one day about money and finances. I went to a public university, where all employee’s salaries were made public. I knew many of the faculty members had salaries in the $130,000’s – $150,000’s and I remember thinking how “rich” they were, making that type of money! In that conversation about money and finances, I remember my mentor telling me, “Expenses rise to meet income.” The implication was that money is always tight, even with steady raises across time, because lifestyle creep makes it so.
I remember making an internal vow to myself, not to let that happen to me. I’m a naturally frugal person. I LOVE hand-me-downs from friends – be they clothes, furniture, etc. Heck, I even take my next-door neighbor’s food if she’s bought something, tried it once, and decided she didn’t like it (note: I know and trust this neighbor…I wouldn’t take opened food from just anyone, lol).
My husband and I have also been blessed with receiving modest raises over the past couple of years. And there have been times in the past when I’ve received relatively substantial raises, too (one time a nearly 50% raise, and another time a 35% raise!). I wanted to share some tips on how I’ve tried to combat the “lifestyle creep” that can happen with income increases.
How I Avoid Lifestyle Creep:
1. Keep fixed expenses low.
Our biggest bill is our mortgage and, therefore, it was important for us to keep our mortgage well within our means. When we were first house-hunting back in 2020, I remember being qualified to buy homes in the 500-600’s. I was beyond shocked that we would qualify for that amount. Had we bought a home at that price point, we most certainly would’ve been “house poor.” The monthly payments, alone, would have made us cash-strapped. There’s no way we would be able to afford the hefty savings and investing that we wanted. Much less the vacations our family enjoys.
Instead of buying the big, beautiful, brand-new home, I fell in love with that cost $500,000 as a base (plus all the upgrades for lot placement, upgraded features, etc.)….we went with a house that was listed as a short sale for half the price. And then we put down a 20% down payment on top of it. Now, our mortgage costs less than the rent at my previous home from when I was single.
2. Buy a used car and drive it until the wheels fall off.
Maybe it’s in my blood to be frugal (my dad was a financial advisor and his dad had worked in corporate finance for Shell Oil back in the 60s and 70s.). For whatever reason, I’ve always been keen on savings and have had an interest in personal finance. As a child, I remember hearing that most millionaires never buy a new car. As an adult, I’ve taken a special interest in the “Millionaire Hour” on the Dave Ramsey show, where Dave interviews millionaires about how they attained their wealth. Anecdotally, his evidence also seems to conclude that *most* (not all) millionaires buy used.
It just makes sense. Cars go down in value, so try to buy low. Spend as little on a reasonable car that meets your needs as possible. This is what I’ve always done. I kept my last car for 10 years (nearly 200,000 miles), and only finally replaced it when the constant repair work was costing more than a car payment would cost.
The car I replaced it with is used. I had a few “must have” requirements that may be seen as extravagant. For example, I insisted on something larger with 3rd-row seating so I could drive my kids’ friends around with us. And also so we’d have a more comfortable road-trip experience when we drive back and forth to visit family in Texas. But I selected a very reasonable car that fit my must have’s. Like the house (where I saw and fell in love with a much fancier home, only to buy a more economical one…), I found and fell in love with a beautiful, brand-new car that had all the bells and whistles. 360-degree cameras and wireless phone charging and air-conditioned seats were among its features. But it cost $15,000 MORE than the car I ended up ultimately purchasing. I just couldn’t swallow that price tag. I went with the more reasonable car instead, purchasing it in October of 2021. And I have a goal to get it paid off by the end of this year.
3. Budget, budget, budget
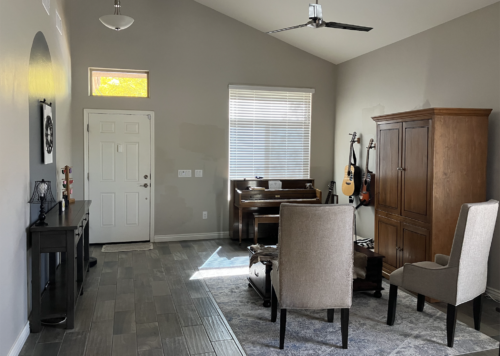
In a surprise to no one…..one of the best ways to avoid lifestyle creep is to budget your money! Avoid impulsive purchases. Heck, stay out of stores, in general! You don’t need to have *everything you want* right this second. We closed on our home in August 2020 and it has taken years for us to furnish it. We have a formal living room that sat empty for the entire first year we lived here. Over time, it has evolved into our music room. We already owned the guitars, but we got a free piano from a neighbor who was moving, free chairs from a neighbor who was upgrading theirs, and a new-to-us entry hall table for $20 from a yard sale.
I love how our little formal living room has come together, and it’s been incredibly inexpensive to pull together, but it didn’t happen all at once. We lived with the space being empty and barren for a long time. And it’s all worked out in the end because we love it now and we’ve been able to slowly add purchased pieces (like the big clock face, and a new rug) over time, as they fit into our budget. Sometimes my husband jokes that we have a hodgepodge of neighbor’s furniture leftovers and “rejected items.” But I think the colors all pull together nicely, and I personally really like the style we’ve created in our home. It’s not perfect. But it’s ours!
4. Out of sight, out of mind
Another way to keep lifestyle creep at bay when you get a raise is to hide the money away! No, I don’t mean stocking it under mattresses or in couch cushions. But, rather, to increase retirement contributions, 529 contributions, or HSA contributions by an equivalent amount as the raise.
Every time I’ve gotten a raise, I like to factor a little bit of the extra into my budget. But most of it, I keep out of the budget all together (because my budget is based on take-home pay, and my investments occur automatically before the paycheck hits my bank account). For example, let’s say I received a raise that amounted to about an extra $200/paycheck. I might allow an extra $40-50 into my monthly budget to help pad living expenses, but the rest, I’d put directly into other investment vehicles. No better way to keep your money than by keeping it out of the checking account! Out of sight, out of mind! 😉
5. Don’t Keep up with the Jones’s
Ideally, I would say it helps to surround yourself with like-minded people who share similar financial goals and values. But that’s not always possible. So even if you have big-spender friends, don’t let their purchase decisions affect you. Don’t let their clothes, lavish trips, major home renovations, or perfect home furnishings make you jealous. Know that you are playing the long game. Most people have debt. That’s the “norm.” I’m trying to live that debt-free life. That’s my ultimate goal.
Additionally, be aware that you don’t always know the inner workings of everyone’s financial situation. My husband and I had casually chatted about one of our couple friends. The husband worked for the government. Like my ability to look up the salary of my public university mentors, I was able to look up this person’s salary too. We were stumped on how the family could afford to have a homemaker-wife, 5 children, and to take all the vacations and pay for all the competitive sports team fees, and all the fancy things they seemed to own and/or do. It’s been years that we’ve known these people and I just recently learned that, prior to having children, they owned a small business that had gained some popularity and they were able to sell for a hefty sum. Even though I could look up the husband’s salary through public databases, that data didn’t account for the very sizeable nest egg that they’d established prior to ever having children and the career he has at this point in life. So, you just never know what’s in someone else’s financial background.
Likewise, someone might look up my salary and think I’m “rich” (just like I had thought about my mentor all those years ago). They don’t know that my education caused me to take on 6-figure debt and that I’m still to this day, a whole 10 years later, trying to dig my way out of that hole.
I’m the closest I’ve ever been and I’m determined to get there. Consumer debt-free by the end of the year (when I pay off my car), and then after that, I’ll have just $20,000 left on my long-lived student loans. Or less (pending what happens with all the student loan forgiveness stuff…). I am *so close* and I cannot wait to hit that mark! And then, next, we’ll turn our sights to the home mortgage. How great it must feel to step on the lawn when you know you fully own every blade of that grass. I cannot wait!
Do you have any tips for how to avoid lifestyle creep?
Read More:
CPA versus Certified Tax Preparer…Is It Worth It?
6 Travel Hacks to Save Money While Traveling
Hi, I’m Ashley! Arizonan on paper, Texan at heart. Lover of running, blogging, and all things cheeeeese. Early 40s, married mother of twins, and working in academia. Currently working toward financial independence with the goal of (hopefully!) retiring early at 50.