:::: MENU ::::

Posts tagged with: tomato soup

Grateful for What Is

by

I have a secret I’ve been keeping from you all. I recently applied for a very high-level role in academic administration. While I wasn’t sure that I wanted to go into academic admin, the job description sounded like it was written specifically for me. It was in perfect alignment with my skills, talents, and interests. I had to go for it.

I made it through multiple rounds of interviews, making it to the top 3 who interviewed in the final round for the role. And a couple of weeks ago, I got the call – they decided to go in another direction.

At first, I was disappointed, of course. I had really prepared for this interview. I’d done everything right! I’d bought a new suit (it’s not common to wear full suits in my current position, and though I own a couple of suits, one is too small and one is too large – a testament to my fluctuating waistline across the last decade – ha! So I bought a brand new one in my current size). I also paid to have my resume printed on high-quality paper so I could pass it out during face-to-face interviews. I even created and printed an Impact Report I’d made to show my accomplishments during my time in my current role. I really prepared for the interview, practicing my responses to questions I may encounter, and thinking about what I would bring to the role. I think I made a good impression, and I could tell that the committee, and later higher-ups, were impressed with my responses. I followed up after the interview with personal emails to the hiring committee and thanked them for their time and efforts.

I had visualized myself in the role. Saw myself driving into campus and getting to work each day. I was excited about the prospect of making a larger impact across an entire campus community (whereas the impact of my work now is mostly limited to within my own department).

But then it’s funny how things happen. The day I received the call, I actually couldn’t answer when the call came through. It was 4pm on a workday. I was home (not on campus) and was dealing with a minor emergency with my children. I wasn’t able to pick up the call and had to schedule a call back for the next day. I thought to myself, “If I can’t even take an important phone call…and it’s during work hours still…how on earth am I going to be able to commit to being on campus 5 days/week from 8am-5pm + occasional nights and weekends?!”

Since then, there’s been more parenting-related drama. Nothing major, and I don’t want to infringe on my teens’ privacy by going into it. But suffice it to say there have been things that have required my time and attention. Yes, even during work hours.

Also, this semester has been pretty intense for me. I’m teaching back in person again (for the first time in 8+ years), and it has been a big transition since I’ve been teaching fully online for the better part of a decade. Going to campus so much more frequently has really been an adjustment. These are first-world problems, but I’ve been joking to my husband (who routinely works 50+ hours/week outside the home), “How do you do this?”

I’ve been so spoiled to work mostly from home! I’ve always been around if there’s a delivery that needs a signature, or if there’s a repair person coming to fix an appliance. I can start a load of laundry in between Zoom meetings, and there’s zero commute time, so I have more time to exercise, walk the dog, prep dinner, etc.
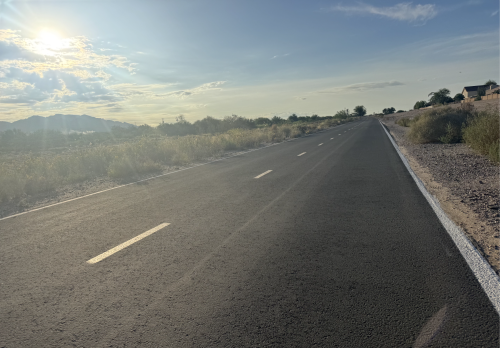
A morning walk before work. Grateful for the time and flexibility to enjoy it.

In the end, I’m grateful for what is. The fact that I did not get this job. Yes, maybe it could have led to more money and prestige. But my freedom and flexibility are worth their weight in gold. I could not trade my current life for that of someone who is expected to be at work 45+ hours/week. Really, truly – you all amaze me! I legitimately do not know how you do it and keep a house running and raise children and all the things!

I’m grateful to be in a place where I can recognize that my time has value. And that my flexible schedule has value, too. I’m grateful to have been put in a position where I had to weigh these things and grateful – so, so grateful – that I don’t have to make a choice between career and caregiving. That my job allows me adequate time and flexibility to do both, while still earning a good living.

Sometimes, all we need is a little perspective to realize how good we already have it.

What are you grateful for?
How Does a Divorce Impact Your Retirement Plans?

by

Divorce can affect nearly every part of your financial life, including plans that may have taken decades to build. Retirement savings are often among a couple’s most valuable assets, which means dividing them can significantly change what retirement looks like for both spouses. Even when retirement is years away, decisions made during a divorce can influence future income, taxes, savings goals, and estate plans.

Understanding these potential effects can make it easier to adjust your financial strategy and begin planning for retirement as an individual rather than as part of a couple.

Retirement Assets May Need to Be Divided

Retirement accounts accumulated during a marriage may be considered marital property, depending on applicable state law and the circumstances of the marriage. This can include employer-sponsored retirement plans, pensions, and certain portions of individual retirement accounts.

According to the IRS, pensions, 401(k)s, and IRAs often require specialized calculations to determine the marital portion and tax implications. The process is not always as simple as checking the current account balance and dividing it in half. Contributions made before the marriage, investment growth, pension formulas, and other factors can affect how much of an account is subject to division.

Certain employer retirement plans may require a qualified domestic relations order, commonly called a QDRO, before benefits can be paid to a former spouse. The IRS explains that a QDRO can assign all or a portion of qualifying retirement benefits to a spouse or former spouse.

Your Retirement Timeline Could Change

A divorce can reduce the retirement resources each spouse expected to have available. Someone who originally planned to retire at 60, for example, may discover that continuing to work for several additional years would make the new financial picture more manageable.

After a divorce, it can be helpful to recalculate how much you will need to save based on your individual circumstances. Consider expected housing costs, health care expenses, insurance, everyday spending, and the lifestyle you want during retirement. You may need to increase retirement contributions or reconsider the age at which you plan to stop working.

At the same time, divorce does not automatically mean that your retirement goals are out of reach. It may simply require developing a new strategy based on the assets and income available to you after the marriage ends.

Taxes Can Affect Your New Financial Strategy

Taxes are another important consideration when restructuring retirement plans after divorce. Two retirement accounts with identical balances do not necessarily have the same after-tax value. Traditional retirement accounts generally involve taxes when qualifying distributions are eventually taken, while Roth accounts operate under different tax rules.

According to the Internal Revenue Service website, individual income tax is one of the primary subjects categorized under its individual tax data section. For someone going through a divorce, understanding how income taxes interact with retirement distributions and other financial changes can be an important part of long-term planning.

Divorce can also change filing status and other tax considerations. The IRS notes that people who are legally divorced by the end of the tax year generally file as single unless they qualify for another status, such as head of household. These changes can affect the broader financial assumptions used when creating a retirement budget.

Social Security May Become Part of the Conversation

Social Security can also influence retirement planning after divorce. Depending on factors such as the length of the marriage, age, and eligibility requirements, a divorced person may potentially qualify for benefits based on a former spouse’s work record.

Because Social Security may represent a meaningful portion of retirement income, it should be included when recalculating future income needs. However, it is important not to assume that benefits will completely replace retirement assets lost or divided during divorce.

Instead, Social Security should be considered alongside personal retirement accounts, pensions, savings, investments, and other potential sources of income. Creating a complete picture can help establish more realistic retirement savings targets.

Your Estate Plan Should Be Revisited

Divorce does more than divide existing property. It can also change who you want to receive your assets or make important decisions on your behalf in the future. Retirement account beneficiaries, wills, trusts, powers of attorney, and other estate planning documents may all deserve another look after a marriage ends.

According to Kiplinger, only 24% of American adults have an estate plan, leaving the majority at risk for legal complications and unnecessary tax burdens. Divorce provides an especially important reason to review these arrangements because documents created during the marriage may no longer reflect your intentions.

Retirement plan beneficiary designations deserve particular attention. The IRS recommends that divorced participants contact their employer or plan administrator about changing beneficiaries for benefits that are not otherwise controlled by a court order.

Your Monthly Retirement Budget May Look Different

Retirement planning as a single person can produce a very different budget from planning as a married couple. Housing expenses, utilities, transportation, insurance, and other costs that were previously shared may now need to be covered independently.

Creating a new projected retirement budget can show whether your current savings rate is sufficient. This process may reveal opportunities to reduce future expenses, increase contributions, or modify investment and retirement-income strategies.

It is also worth rebuilding an emergency fund after divorce if savings were used for legal fees, moving expenses, or establishing a new household. Having accessible savings can help prevent unexpected expenses from forcing you to withdraw money from retirement accounts prematurely.

Rebuilding Your Retirement Plan After Divorce

Divorce can create uncertainty about retirement, but a revised plan can provide a clearer path forward. Start by determining exactly which retirement assets remain yours, reviewing beneficiary information, estimating future expenses, and establishing updated savings goals.

Financial, tax, and legal professionals may also be useful when retirement assets are complicated. Pensions, employer-sponsored accounts, tax consequences, and court orders can involve rules that are difficult to navigate without specialized knowledge.

Most importantly, treat your old retirement plan as a starting point rather than something that must remain unchanged. Your financial circumstances may be different after divorce, but adjusting your savings strategy, timeline, budget, and estate plan can help you build a retirement plan that reflects your new situation.

1 2 3 … 2,045