:::: MENU ::::

Posts tagged with: child support

How Much Money Can Regular Furnace Maintenance Save You?

by

When household expenses start adding up, furnace maintenance may seem like a cost that can be postponed. After all, if the system is still producing heat, why pay for a service visit? However, routine maintenance can help homeowners protect their heating investment, avoid preventable problems, and potentially delay the expense of replacing an aging furnace. Understanding how often your system needs attention can help you make more informed decisions about where your home maintenance budget goes.

Protect Your Furnace Investment

A furnace is a significant home expense, so getting as much useful life from the system as possible can make a difference to your long-term budget. Regular maintenance gives a technician an opportunity to inspect the system, identify developing issues, and address problems before they become more serious.

According to Service Titan, a furnace can have a lifespan of up to 15 years. While maintenance cannot guarantee that a furnace will reach that age, keeping up with recommended service can help homeowners avoid neglecting a system that still has useful life remaining. Extending the time between replacement purchases can ultimately help reduce the financial burden associated with buying and installing a new heating system.

Maintenance can also help homeowners make better replacement decisions. Instead of replacing a furnace because of an unexpected failure, routine inspections may give you more time to evaluate repair costs, compare replacement options, and plan for the expense.

Schedule Maintenance Before Small Problems Become Expensive

Skipping a maintenance appointment can be tempting when you’re trying to save money. However, postponing routine service may mean missing an opportunity to identify issues while they are still manageable. A technician can inspect key components and determine whether something needs attention before it interferes with the furnace’s operation.

According to This Old House, homeowners should have their furnaces maintained at least once every 12 months. Scheduling this service regularly can make furnace care easier to budget because it turns maintenance into a predictable household expense rather than something you address only after a breakdown.

Regular service may also help homeowners prepare for the heating season. Taking care of maintenance before the furnace is needed regularly can provide an opportunity to discover potential concerns before they become urgent. This can be especially valuable during colder weather, when an unexpected heating problem could require a more immediate and potentially costly repair.

Know Whether Your Furnace Needs More Frequent Service

Not every heating system has identical maintenance needs. The type of furnace in your home can affect how frequently professional service is recommended. Knowing your system’s requirements can help you avoid spending money unnecessarily while still keeping up with appropriate maintenance.

For homeowners with oil-fired furnaces, the recommended schedule may be more frequent. According to Salt Air, an oil-fired furnace requires servicing every 6 months. Following this schedule can help homeowners stay ahead of maintenance needs rather than waiting until the system develops a noticeable problem.

Although more frequent service means additional maintenance expenses, it is important to consider those costs alongside the potential expense of neglecting the system. A maintenance schedule tailored to your furnace can help protect its operation and give you a clearer picture of its condition.

Consider Maintenance as Part of Your Home Budget

The cost of furnace maintenance is only one part of the financial picture. Homeowners also need to consider potential repairs, energy costs, and eventually replacing the system. A maintenance appointment may seem like an extra expense, but budgeting for routine service can make heating costs more predictable.

It can also help to keep records of maintenance visits and repairs. Over time, these records can show how frequently the furnace requires attention and whether repair expenses are beginning to increase. That information can be useful when deciding whether continuing to repair an older system makes financial sense.

Make Furnace Maintenance a Regular Expense

Regular furnace maintenance may not eliminate every repair or prevent a furnace from eventually needing replacement, but it can help homeowners take a proactive approach to managing heating expenses. Keeping the system maintained, following the appropriate service schedule, and monitoring its condition can all contribute to more predictable homeownership costs.

Rather than viewing furnace maintenance as simply another bill, consider it part of protecting one of your home’s major mechanical systems. A relatively routine investment in upkeep may help you get more value from your furnace and avoid some of the financial surprises that can come with an unexpected heating problem.
Raising Financially Smart Teens: What Should We Teach Them About Their First Paychecks?

by

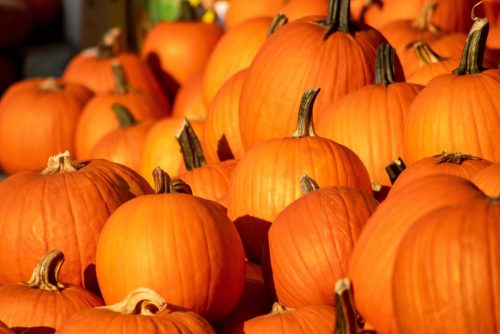
pumpkins in a pile
A new season, and a new season of financial lessons.

Big news around here – my teenagers got their first “real” jobs!! They were both hired as seasonal workers at the Pumpkin Patch. It’s only 5 weekends in the month of October, but it’s a perfect first entry-point to the workforce.

Caveat: I say “real” job with quotations because they have worked for me (for my business), and also done odd jobs like pet-sitting and babysitting. But this is the first W2 position in their lives.

I love that it’s short-term because we have a pretty packed schedule in-between all the new High School events (football games! dances!) and their sports schedules. It’s weekends-only, and only for 5 weeks. Even so, this is “big money” for them! The minimum wage in Arizona is $15.15/hour and, boy, do they each have dollar signs in their eyes, eagerly awaiting the Pumpkin Patch opening!

Suddenly, I realized we’ve entered a whole new phase of parenting: teaching our kids what to do with money they’ve earned themselves. This raises all sorts of questions for me and I’d love to solicit advice from those of you who have gone before. ?

How much should they save?

Should I require them to save a certain percentage, or let them have free rein of how they save or spend their money?

Should they invest in their Roth IRAs? How much?

They already have Roth IRA accounts since they work for me, and I ensure deposits are made into their accounts from their earnings. But now that they have a W2 job…should I also encourage/require they invest some of those funds as well? What percentage?

Should they have a “giving” requirement?

When I was growing up, I remember my parents getting me a piggy bank with 3 distinct categories: saving, tithing, and spending. From an early age, I was encouraged (or…required), to put a portion of my money aside for tithing.

I do think there’s a real benefit of giving back to others. Even if it’s not tithing to a church, I’ve encouraged the girls to make donations in the past when they’ve received an influx of money, like for a birthday or Christmas. They’ve donated  to our local animal shelter, which has an online Amazon wish list that lets you pick specific items that you want to give to the pets there. So we could do something like that with a small percentage of their money. What do you think?

What’s the best savings account(s) for kids?

Right now, we’ve just been doing Greenlight cards for the kids (<referral link. If you sign up, we each get some free money!). Through Greenlight, I can designate a portion of funds be put into spending versus savings, and I like that it gives me the ability as a parent to approve (or decline) purchases. For instance, most of the girls’ money stays in savings and they cannot move it to spending without permission. 

It has initiated great conversations about what is appropriate (or not) for spending. Like the one time the girls decided to make each other gift baskets (for no reason – not a birthday or anything) and set a limit of $60/basket!

I love the thought and consideration since they were doing it for each other. But $60/basket is insane. Their allowance is only $25/month, so we’re talking over 2 months’ worth of allowance going into a completely random just-for-fun gift. We had a big discussion about how I loved where their hearts were, but the value of the gift was out of proportion with their budgets.

Anyway….I’ve been thinking I need to open up traditional savings and checking accounts for the girls and to get “normal” debit cards for them at some point. Is now the time? If so, what are the best accounts for teens? I want something that’s easy to open and access, and having some built-in parental controls would be great. I have accounts at Bank of America and Capital One, so if one of them is good for teens, it’d be a bonus that I already bank there.

How much do I let them screw up?

Back to the gift basket story…. part of me thinks this is a good time to let the kids make some questionable purchases. The stakes are low right now. They don’t have any bills they have to pay.

Is blowing $100 on something ridiculous actually a great way to learn that blowing $100 on something ridiculous doesn’t feel great afterward? Where’s the line between teaching good financial habits and controlling their money so much that they never learn to manage it themselves?

Do you suggest any good resources for teens to learn financial literacy?

Obviously, I’m a bit obsessed with money (as evidenced by blogging at a get-out-of-debt blog for a decade now, lol). My kids are less so. They’re not oblivious to it – we have lots of financial conversations. But I think they’re now at a life juncture where they could stand to learn more.

Do you have any books, podcasts, YouTube channels or other resources you’d recommend specifically for a teenager earning their first paycheck? Not something stuffy “Elder Millenials” (as they call me) would be into, but something teens would actually find interesting?

Honestly, I will take all the help I can get! We’re soon going to be getting into all kinds of financial conversations with the kids. When they’re able to drive a whole new world will open.

I’d love your advice and input while we’re on the front end of this whole kids-working-and-earning-money adventure. If you’ve already raised teenagers through this stage, what worked? What didn’t? What do you wish you had done differently? And if you have teens now, how are you handling their money?

I’m taking notes.