:::: MENU ::::

Oh, what a feeling…

by

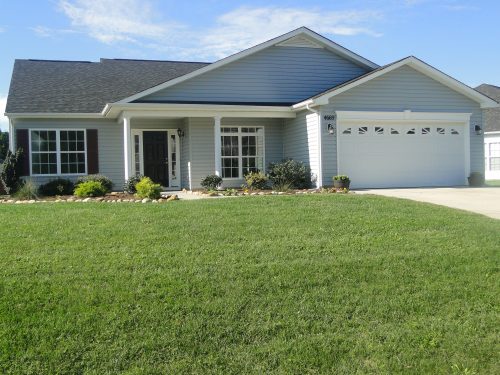
We are finally on the final stages of getting the house ready to go on the market.  There have certainly been times during these two months that I’ve wondered “why me?” but I’ve held on to the fact that in every bump in my life I’ve been able to look back and find the reason.  This experience has taught me so much, not just about money but about selling a house.  I’ve never sold a house before as my only other house I owned was sold as a spousal buy out in my divorce.  Okay, so those are the obvious lessons.

I’ve also learned more about maintaining a home, fixing a home and the big one, having money!  I know that sounds crazy since I’m pouring everything into the house and living.  But for these past months instead of paying debt extras, etc. I’ve been hoarding money for things to do with the house.  Granted I’m tapped out now, but for these last couple of weeks, when I needed to buy something for the house or pay someone for work…I just paid it.  I didn’t have to budget for it, wonder if I had it, etc.

I’ve been living so close to the wire these past years, especially this past year that I’ve been so focused on paying off debt that I rarely could spend money without really thinking it through, thinking what was coming in the next four weeks, etc. So this has definitely inspired me to consider changing out I manage my money, no just after the debt payoff is done, but even maybe some small changes now.

So I’ve been considering a couple of things:

I’ve been inspired by Ashley’s living on last month’s income, but that would take me a few months of no debt pay offs to get far enough ahead and I’m not sure I am willing to do that.

My emergency fund is steadily growing from my part time job so I could use that as my “cushion” but I think I’m better off leaving it be and going back to forgetting it’s there.

I could take a month or so to pad my primary checking account with a few extra hundred.

I’m not sure if any of these will work, but I do know that these weeks have definitely taught me some very valuable lessons on finances and home maintenance and selling.   I will feel so much better when I (and my dad) can have complete closure on this issue.  And even though I no longer carry the financial burden of the house, I certainly feel the responsibility for putting my dad is this situation. The house goes on the market on Saturday…please pray for a quick sale.
DSC05483

September Budget Update

by

This month we had $6317 to work with for income. Little heads up….we went over our budget. The excess was taken from our extra savings. Here’s how we stacked up in each category:

PlacePlanned BudgetActual Spent
Rent10551055
Electricity260245
Water6561
Natural gas2014
Sprint (2 lines)115114
Cable/Internet100100
Car Insurance104103
Health Insurance350350
Trash3535
Debt20091779
Miscellaneous300366
Groceries400483
Baby Purchases12001077
Gasoline100111
Saving for Irregular Expenses445445
Total Budgeted65586338


So our actual spent ($6338) minus our income for the month ($6317) means we spent over budget by $21. Not too terrible, but there were some categories of spending I’d like to zero in on and give some additional details….

First, you’ll notice that less was spent in debt payments than was initially planned. I hate to put less toward debt, but here’s what happened….

Do you remember when I moved my student loans to be Income Based Repayment (IBR)? Welllllll, there was some confusion with this. I realize how irresponsible and airheaded it sounds for me to admit that I didn’t realize what was happening with these payments, but….yeah. That’s kind of what happened. Apparently, there was a “hiccup” with my ACS student loan IBR payment. And by “hiccup”, I mean I was actually paying the full payment rather than the lower income-based payment. I don’t know how this happened. And, actually, it would have just continued like that forever if I hadn’t made a call to the company about something totally unrelated and discovered completely coincidentally that my payment was not, in fact, in IBR status. So that changed in a hurry. This lowered my monthly ACS payment from $247/month down to $77/month. Remember – while in IBR status, any unpaid interest is forgiven for subsidized loans, so I consider this a good deal since this extra money could (theoretically) go toward other debts.

Of course, this month we did not have any extra money to go toward additional debt. Womp, womp!!!! I also paid less toward our car loan than I had originally hoped (I made a $1,000 payment this month – still more than the minimum, but not as much as I’d hoped).

I was over on our grocery budget, but I’m hoping the new modified money envelope system I’ll be using this month will help with that.

I was also over in miscellaneous. Miscellaneous is broken down into four sub-categories:

  • Entertainment: budgeted = $20, actual spent = $8
  • Eating out: budgeted = $100, actual spent = $136
  • Personal maintenance: budgeted = $30, actual spent = $15
  • Other: budgeted = $150, actual spent = $207

Total budgeted = $300, actual spent = $366

Again, the modified food envelope should help curb my eating out spending. The “other” category spending was, in my opinion, pretty unavoidable. $94 was spent on my annual life insurance premium (side note: I mentioned in this post that I increased my semi-annual savings to account for this expense for future years’ annual payments). If it weren’t for this expense we would have been well under-budget in this category so I’m not concerned with the other much smaller purchases made from this category.

So there you have it. We did still go over our income, but it wasn’t too bad considering the original planned budget placed us at $200 over our income, so ending at $21 over income isn’t terrible.

This month also turned out to be pretty lackluster in terms of our income (though not as terrible as it could have been). My family was in town all weekend so I didn’t get a chance to write a planned budget post, but I’ll try to get one up either later today or on Tuesday depending on how work stuff goes.