by Matt Fildes
Hey everyone,
Ok, so on Thursday I posted about my latest accomplishment- I paid off debt Sallie Mae 03! But what I didn’t post was… everything else. A couple of you asked if I could post more about me- a valid point which I’m more than happy to share, knowing that people want to hear more than just “blogging away debt”.
So here’s what lead me to…well… here:
I’m currently 28, having just turned 28 last month. I was born and raised in the beautiful (not really, but still awesome) Buffalo, NY with my 2 parents, a younger sister (2 years) and brother (5 years). We lived a very comfortable (for us kids) middle-class life in the suburbs (translation: we looked like we had more money than we did). I grew up with Buffalo Bills, Buffalo Sabres and chicken wings- 3 of my favorite things to this day. Sometime around the age of 10, I decided I wanted to be an engineer, not just any engineer, an Imagineer- a Disney cast member who designs everything in the theme parks. This was my dream and to some extent, still is. After a long road through high school, in which I was quite the trouble maker, I got accepted to a few schools for Mechanical Engineering, two of being University of Miami (FL) and University at Buffalo. Going to U of M was also one of my dreams and I made an early decision to go the summer before my senior year. Sometime during that year, I got the bill for the 1st years tuition- $40,000 FOR. ONE. YEAR. Like I said earlier- I was a screw off and didn’t do any favors for myself in terms of scholarships and grants. After a long talk with my parents we decided that going to University at Buffalo (UB) for $4,000 a semester and living at home made way more sense than going to an out of state, private school.
My freshman year of college I really turned things around- I had relatively high GPA for the program (3.8), worked nearly full time and helped coach my high school wrestling team. This coaching gig gave me the itch to go back and wrestle myself- in college. In high school, I was good but definitely not great. UB was/is a NCAA Division 1 school, meaning you have to be pretty awesome to excel there. So, I transferred. To a private Catholic University in Erie, PA. Why? Because it was the only Division II school that had both a wrestling program AND mechanical engineering. Well, private Catholic University means BIG $$$ (and even more $$$ since I had to take summer classes to catch up due to “nontransferable credits”) and somehow in the course of me deciding the transfer, I lost sight of why I didn’t go to my “dream school” in the first place. Was it a great experience? Most definitely. I met my lifelong friends, gained a tremendous amount of skills wrestling in college and graduated with a degree, a pretty sought after degree, or so I thought…
At the time I graduated in 2009, the economy was already deep in recession (something I think we all remember). It’s hard to find someone who WASN’T affected by all of it. Anyways…getting a job was tough, really tough. I remember sending out 15-20 resumes a day and not getting any calls, let alone interviews. I wasn’t the only one. Of 13 of us in the program, only a couple (2-3) had jobs lined up after graduation, and it was for firms they had internships with. The fear of not being able to pay bills and having to move back in with my parents kept me motivated. Thankfully, I was lucky enough to get an internship in my last semester with the Federal government to work in construction and equally thankfully they had a position open that I could have when I graduated. Problem was, an intern had to work 600 hours before they could be hired full time, so I worked 70 hours a week, while going to school full time (I had to give up wrestling to achieve this). The day after graduation I had a full time job (but not great in the pay department) and was in full time student loan debt.
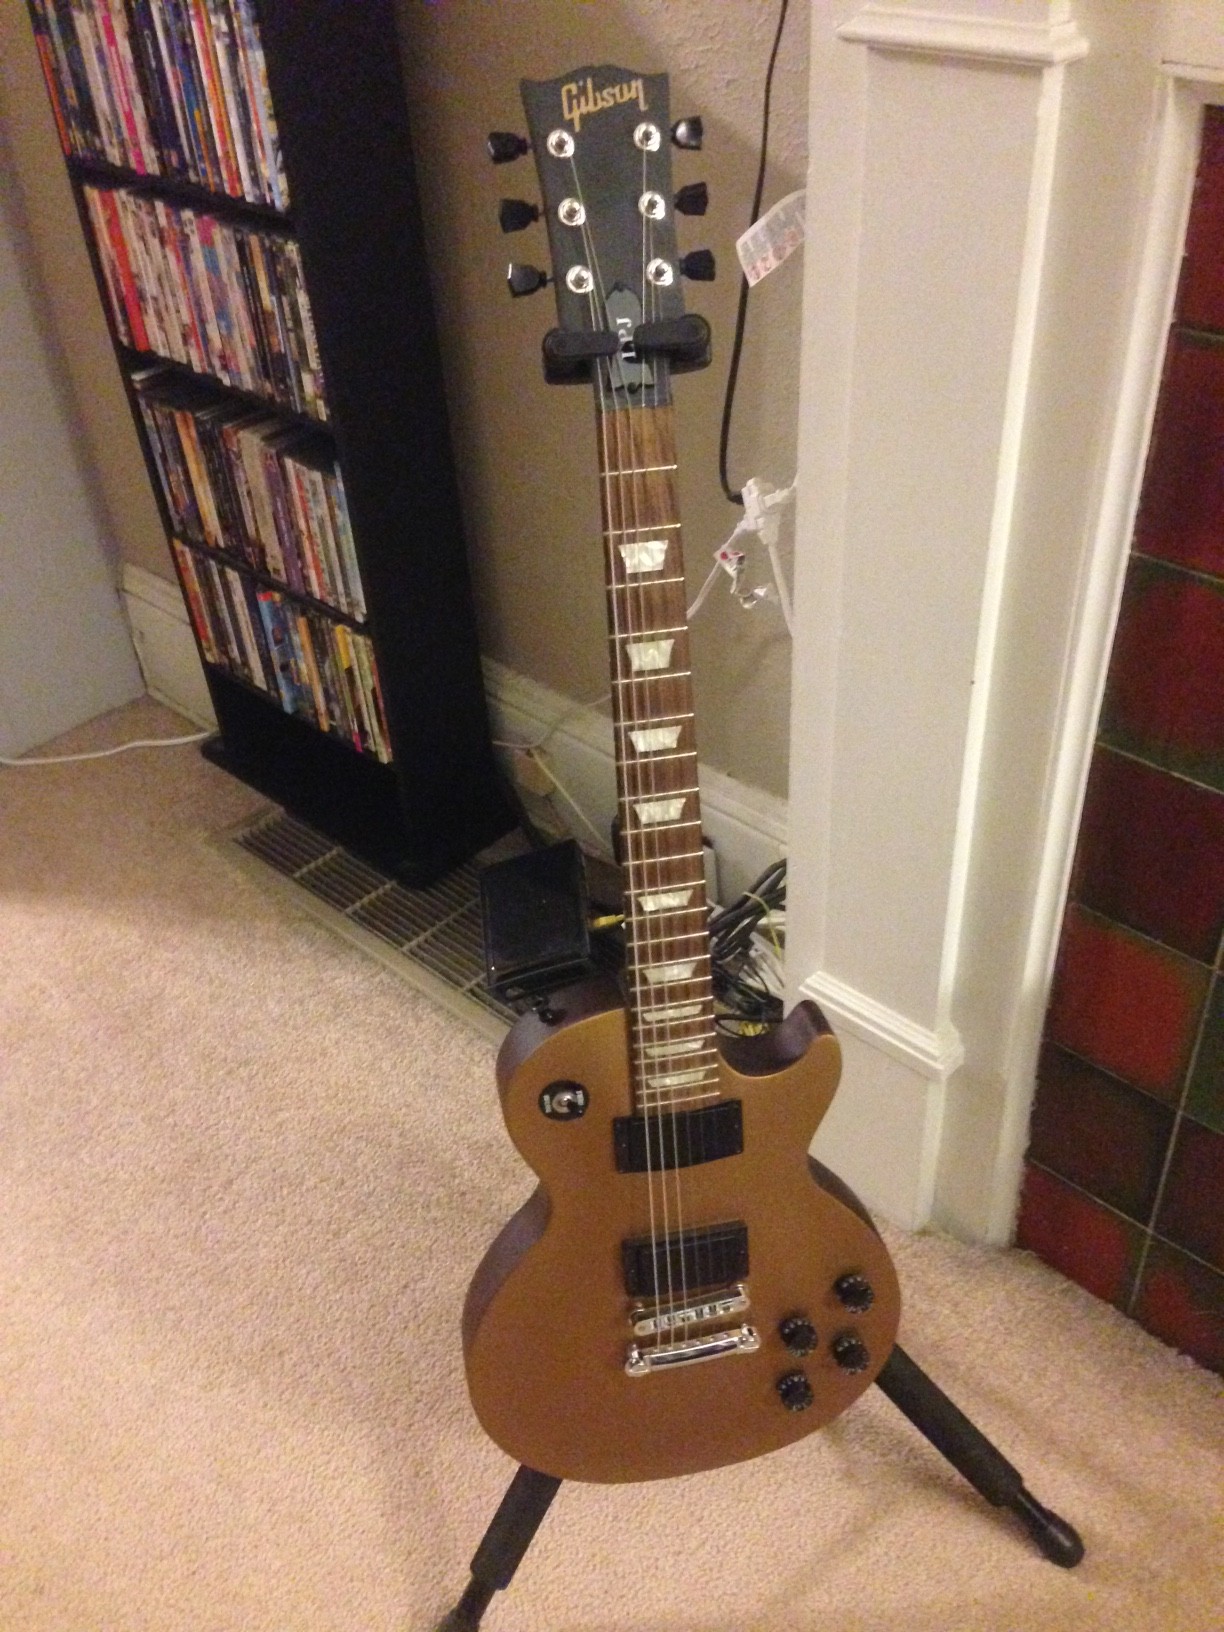
As you’ve all seen from my initial posts, I graduated with $110,000 in student loan debt (now matter how many times I write, it’s still crazy). For 2 years after gradation, I lived in a basement apartment (which had windows, albeit, not good ones) and paid interest only on my largest batch of student loans- the private ones with Sallie Mae. As terrible as it was for a while ( I was only making $50K at the most while I was with the government) this set me up to be disciplined to pay off my debt. Even paying interest ONLY on half I loans my payments still added up to $700 a month. It truly scared me with what could happen if I lost my job and couldn’t pay (reading student loan horror stories on the internet didn’t help any). So I worked form the ground up, putting whatever I could to pay off my debt, even taking a 2nd job for a year busing tables. This also lead to me taking up a whole bunch of hobbies that really don’t cost that much- playing guitar, here’s my current guitar:
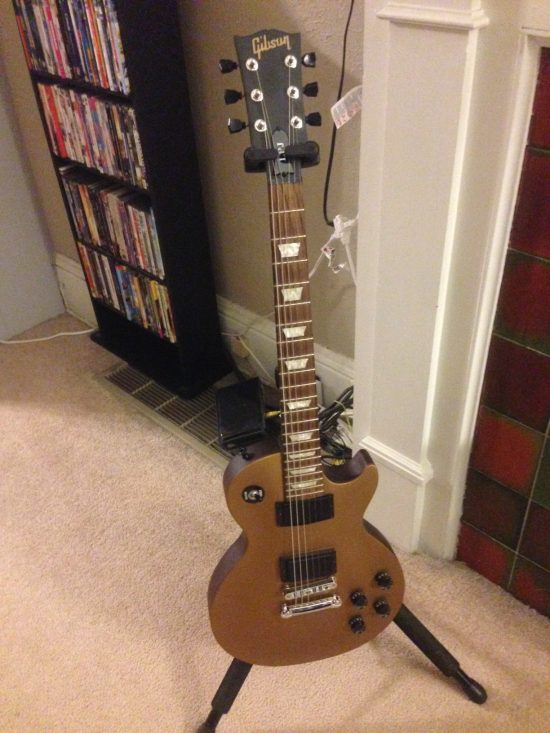
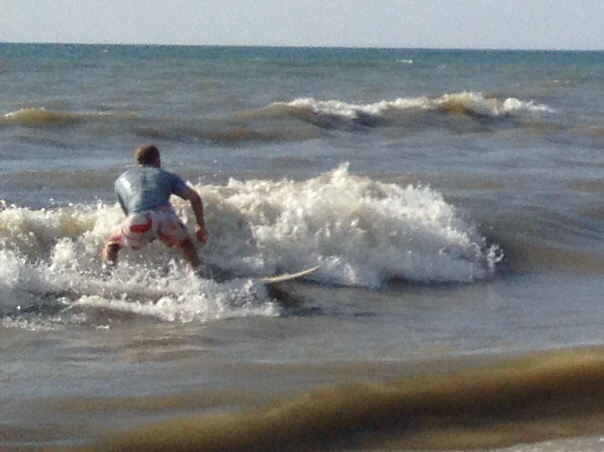
,surfing (yes, you can surf Lake Erie- look up YouTube videos), and here’s proof (that’s me, over the summer):
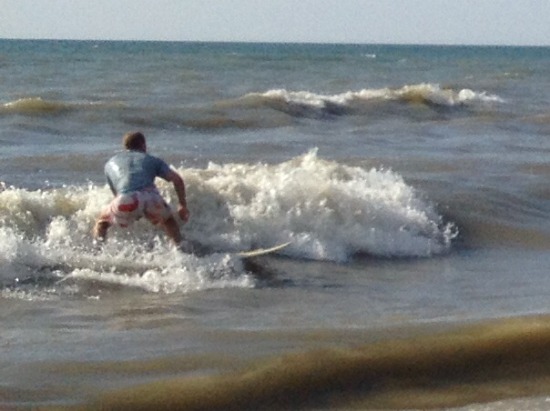
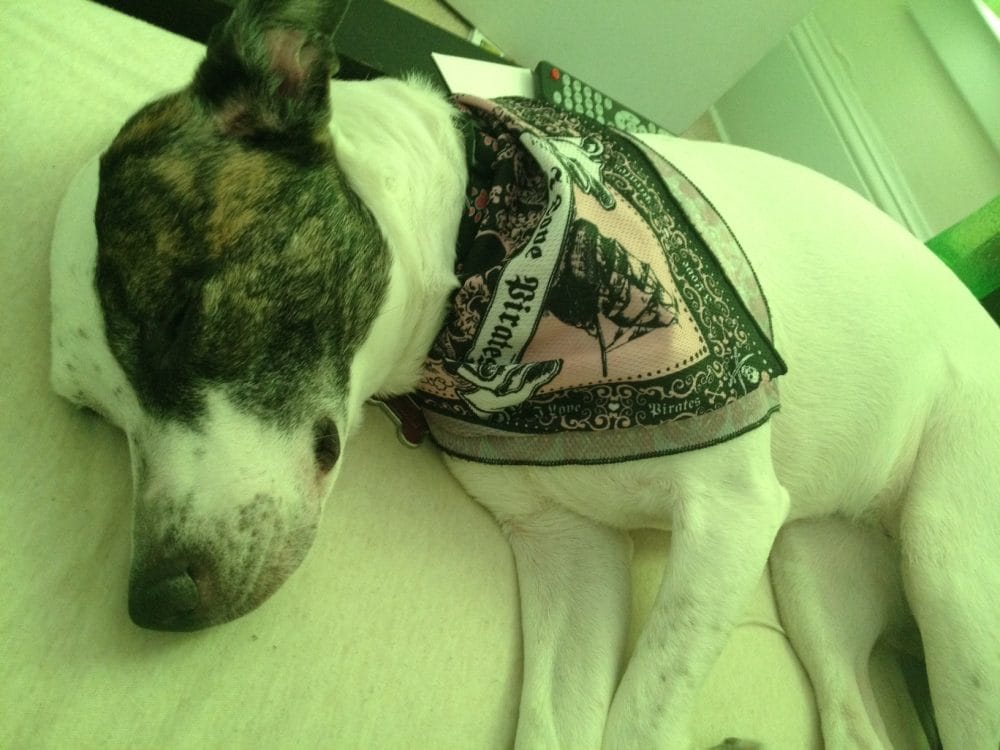
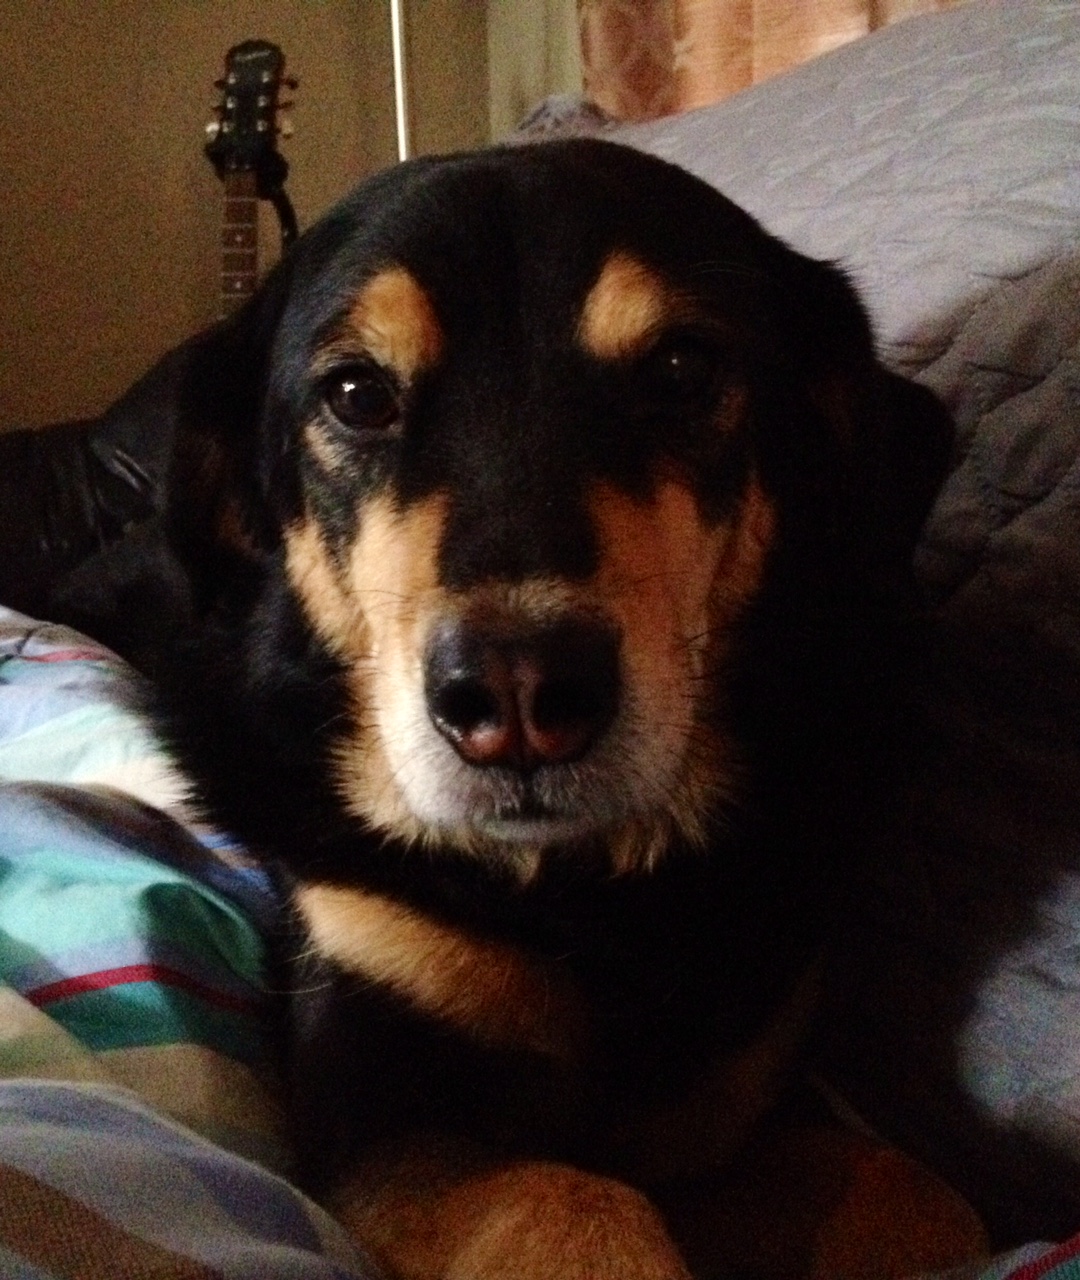
longboarding (the skateboard kind) working out, running and reading. From my intro post, here, and here, you can read my journey form the last five years. I currently “own” a house, which I share with my GF and our 2 dogs: Harlow (the white one, a whippet mix) and Bubba (an Australian Sheppard mix), both rescue dogs:
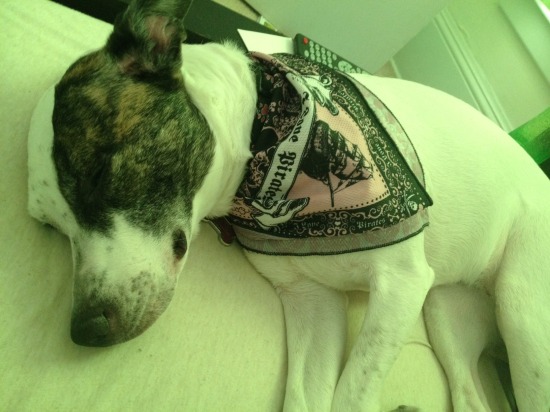
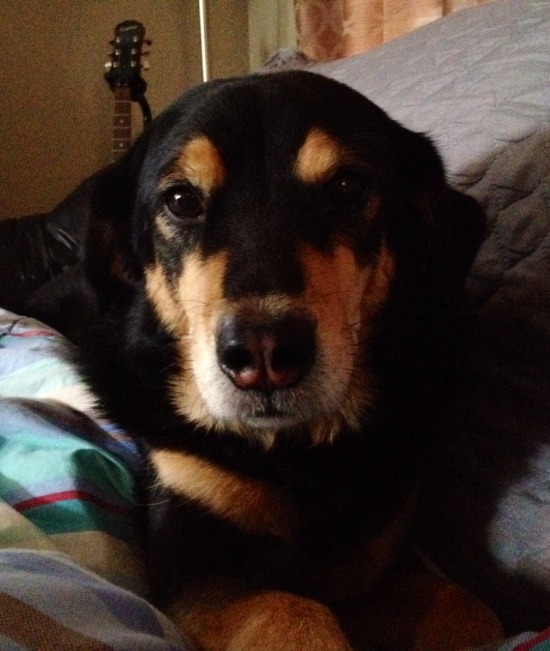
Ok, so that’s pretty much the run-down of my bio. I think a good reason why I don’t post too much info about myself, is because paying off debt is boring, like REALLY boring. I can count on my one hand the amount of times we’ve “gone out” since last summer. I’ve paid off over $48,000 since September of ’09 and in order to do that I’ve cut a lot of money absorbing things out of my life, which gives me little to discuss other that what I’ve posted in the past. What I do love posting about is what’s come up in the past week and what I’m expecting in the week to come that lead to me being able to put a good chuck onto my loans.
I guess here is where I’m looking for some input- what do you guys want to see? I could post weekly updates like I was doing with more insights into my financial plans, or I could most more personal items about my life, like this post…or some mixture in between. Just let me know in the comments!
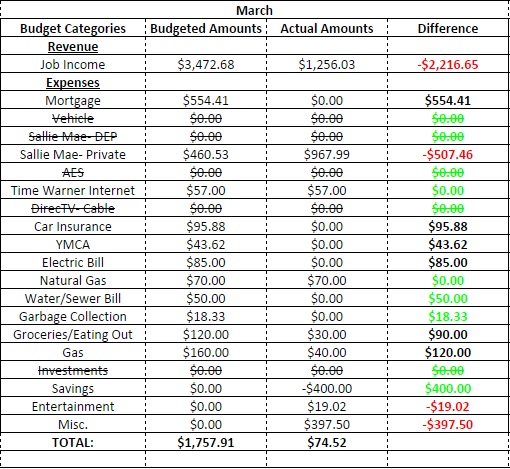
Since this post is already long enough- here’s a quick look into my monthly budget thus far. Big ticket item- had to pay $397.50 at the dentist’s for a crown which came out of my slush fund.
And here’s where my debt balances are:
| Loan Name | Interest Rate | Original Balance- May '09 | Current Balance | Total Paid Off |
|---|
| Sallie Mae 01 | 5.25 | $27,837.24 | $24,462.48 | $3,374.76 |
| Sallie Mae 02 | 4.75 | $22,197.02 | $19,189.15 | $3,007.87 |
| Sallie Mae 03 | 7.75 | $20,692.10 | $0.00
| $20,692.10 |
| Sallie Mae 04 | 5.75 | $10,350.18 | $7,723.61 | $2,626.57 |
| Sallie Mae 05 | 5.25 | $6,096.03 | $4,969.48 | $1,126.55 |
| Sallie Mae 06 and 07 | 4.75 | $6,415.09 | $0.00 | $6,415.09 |
| Sallie Mae- DOE 01 | 5.25 | $5,000.00 | $0.00 | $5,000.00 |
| Sallie Mae- DOE 02 | 5.25 | $3,000.00 | $0.00 | $3,000.00 |
| AES | 6.8 | $9,000.00 | $0.00 | $9,000.00 |
| TOTALS | | $110,587.66 | $56,344.72 | $54,242.94 |
Note to all: I will be now focusing on paying Sallie Mae 05 (the next lowest balance). Interest rate does not concern me at this point since I should have these paid off quick enough that it won’t have a large effect.
Thanks for continuing to allow me to post on this blog and thank you to all the comments on my last posts!