:::: MENU ::::

Housing – Stop!

by

This post will let you know where we are on our housing quest that I brought up in my Year to Build post back in February.  I know many of you are horrified at the thought of me looking to build or buy a home while still in debt, and I totally get that on a financial level.  But on a mom level, this has been a VERY hard pill for me to swallow.  So here’s what I’ve been doing this past two months on this front. (Please note that this post is filled with links to additional information, but none of them are affiliate links, just wanted to show you what I’m talking about more effectively.)

First, I need to make it VERY CLEAR, that not a single dime has been spent on any housing ideas.  I’ve spent a lot of time researching and meeting with people, but no money.  So let’s make sure that is clear first.

As you know, I had an idea that our housing situation was going to change  early year as I drew closer and closer to the idea of not purchasing the home from my dad.  I immediately started with Google searches like “houses for $100K” and “building a house for $10K.”  That brought me to the DIY sites for Yurts, which seem amazing and affordable, but awfully small for us.  From there I researched RV living, bus conversion, tiny houses of all shapes and sizes and then finally stumbled upon this Steelmaster Quonset style home.
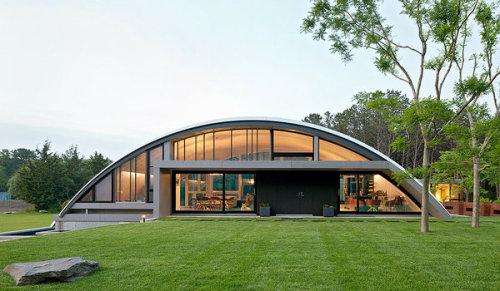
Arc House in East Hampton
Arc House in East Hampton – <a href="http://freshome.com/2013/09/09/surprisingly-adapted-to-a-difficult-site-arc-house-in-east-hampton/" target="_blank">read more here</a>

And that leads me to where I began this year…with this concept and almost a year’s worth of research on building one in a cost effective, energy efficient manner.  We are talking I am now full of knowledge on insulation (blanket vs spray,) heating (radiant vs heat pump,) efficient building practices, direction housing should face for solar, window efficiency and so much more.  I mean lots and lots of data.  I’ve even been reading up on building practices, being your own general contractor, etc.  So when I posted the post in February I had a pretty good idea of what I wanted to do, what my budget was and the only uncertainties were land, and red tape from financiers.

I quickly found a lot I wanted in a rural area.  It’s been on the market for quite a while, is already cleared (used as farmland) and well, I really fell in love during a tour.  It just spoke to my soul.  In fact, as I’m writing this, I’ve just received a message that the owners was to know if I am interested.

Financing a house, especially a build…ugh!  I started with construction loans…20% down, and a 700+ credit score is pretty much across the board requirements.  Yup, I don’t have it.  So I decided to hunker down and really go hard at my debt, thus the 6 month pay off goal came into the forefront.

But then, during my late night ramblings across the internet, I found….the USDA Section 502 Rural Loan Program. The program was designed to reinvigorate lower income rural areas, supporting lower income families to get into modest housing. The county we are looking to move to qualifies across the board, and frankly, I couldn’t consider moving there if I didn’t homeschool.  They will finance 100% with minimal guidelines of what type of housing you can build.  I thought we were home free.

Through all this, I’ve been meeting with contractors and engineers and leaving each meeting a bit wiser and more determined that this was the right course.  And so, two weeks ago, I went into a mortgage office to apply.  And here’s where my dreams derailed quickly:

  1. Evidently I am an authorized user on one of my dad’s high limit credit cards – ding #1.
  2. They will not discount the car payment that my ex-husband is responsible for, meaning it counts against me in my debt to income ratio – ding #2.
  3. Underwriters don’t think they will finance this type of building because there are no local comparables – ding #3.

Obviously, issue #1 and #2, I can do something about, especially since I will be rid of all consumer debt by July.  But #3, just made me cry.  So last week, I took a week off from any thought of housing and every time I thought of it, I said a prayer asking for guidance.  It was a hard week but good to step away and get some perspective.

So I’m back this week and I’m ready to start looking at housing from a different perspective.  The kids and I had a great talk about it this past Friday night as we ate our pasta dinner before Little Gymnast state meet.  So stay tuned for the next chapter of this story….
 

Weekly Debt Update #9- Over the Hump and Future Plans

by


Hope everyone had a great weekend and a great start to the week!

I’ve officially paid off more on my student loans than I owe! I can’t describe just how good that feels (but I can try- amazing!) but I still have a lot of work to do…approximately $55,000 of work. So…I don’t really feel much need to celebrate anything, just take a nice long look at how far I’ve come, then put my nose back to the grindstone.

Here’s what my balances look like as of the 21st (my Navient auto-debit date):

Loan NameInterest RateOriginal Balance- May '09Current BalanceTotal Paid Off
Sallie Mae 015.25$27,837.24$24,224.78$3,612.46
Sallie Mae 024.75$22,197.02$19,006.27$3,190.75
Sallie Mae 037.75$20,692.10$0.00
$20,692.10
Sallie Mae 045.75$10,350.18$7,570.60$2,779.58
Sallie Mae 055.25$6,096.03$4,276.91$1,819.12
Sallie Mae 06 and 074.75$6,415.09$0.00$6,415.09
Sallie Mae- DOE 015.25$5,000.00$0.00$5,000.00
Sallie Mae- DOE 025.25$3,000.00$0.00$3,000.00
AES6.8$9,000.00$0.00$9,000.00
TOTALS$110,587.66$55,078.56$55,509.10

Since last week, I’ve been doing some thinking about what I’m going to do after all my (non-mortgage) debt is gone. I know my number one goal is going to save up 1 years worth of expenses. Basing the 1 year on my current expenses, less the student loans, since I’ve lived my entire adult life on a bare bones budget, I have annual expenses around $15,000. If I throw all the money that I put onto my debt into a savings account, it should take me between 5 and 6 months to do this. I also know that after I save this money I want to catch up my retirement that I missed on this past year, which will go to a Roth IRA- roughly $5,000.

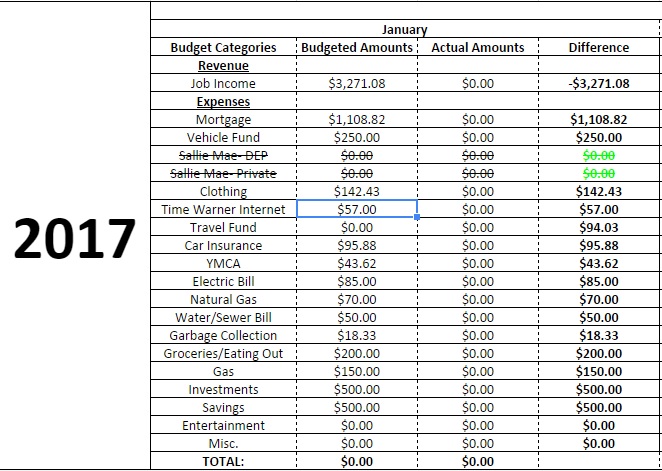
So that’s what I know I want to do for sure. After not, I’m not quite sure at all. I developed a future budget that I could use:

Future Budget

Since I haven’t done any spending in the past few years, I’d like to have budget lines for a future vehicle and/or repairs for my current car (which is already at 86K miles), clothing, and some travel. HOWEVER, I also want to pay 2 mortgage payments monthly and continue to save. One of my biggest inspirations to really start hammering the debt was/is Mr. Money Mustache, so I’d really like to continue living a fairly frugal lifestyle while continuing to save as much as possible. Well- I can’t have it all, so I think this budget is a good balance between spending and saving. And the good news is this is all based on my current pay, which, hopefully, I should be making more in a couple years. I also based my income on the fact I’d like to contribute 5% to our company’s 401K plan to get the most match as I can.

I’d like to hear from people in comments on what you did after you paid off debt- were you to worn out from the payoff that you went into spending mode, or did you continue the lifestyle?

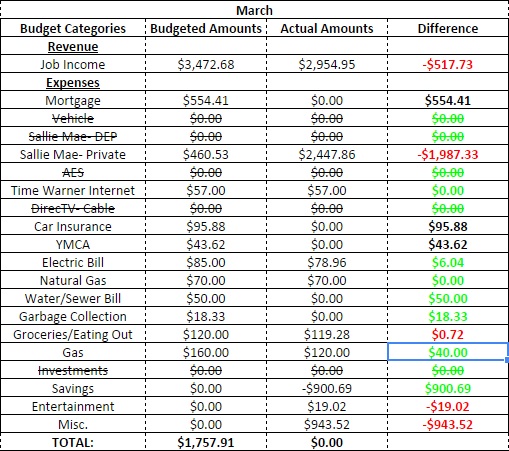
On a budget note, here’s where I currently stand in March:

Weekly Update #9


There’s couple of big items that came up this month (which weren’t all that unexpected): 1) I had a crown put in at the dentist a couple weeks ago. I have insurance, but I owe %50 out of pocket for this type of work. The cost- $397.50. 2) I filed and paid my local taxes. I knew when I withdrew my government retirement account (back in September) I would owe state and local taxes on it when I filed in the new year so I knew this was coming. I paid $700 to PA last month and $310 to the city of Erie over the weekend. 3) I had to take our one dog to vet a couple of weekends ago to have them look at an ear infection and to get her vaccinations. The costs- $132.02, but me and my GF have a plan set up- if it’s “her” dog (the white one, Harlow) that she brought to the relationship, the GF will take care of the vet bills and vice versa for my dog (Bubba, the black one). Since I took Harlow in while my GF worked, she wrote me a check for the visit that I just deposited yesterday and, thus, isn’t reflected in my budget, yet. 4) I had to put down a $100 deposit for the B&B I’m taking my GF to in April to make up for my V-day gift to her (the poorly timed concert tickets :/). I didn’t expect this since I didn’t remember putting a deposit down the last time I booked a room. O well, it just means I’ll pay less when we check out.

I also spent more in the groceries/eating out category than I normally do. I had to go into work for a couple of weekends this month, so I bought breakfast for myself on the way to make it easier to go in. I also had a surprise visit from one of my best friends (who lives in North Carolina) over this weekend. Didn’t spend to much, but I treated him to lunch at Moe’s while he was passing through town. It only cost $25 and he has paid for me more times than I can count in the past, so I owed it to him.

My slush plan is fairly low, much lower than I’d like it to be:

Slush Fund= $1,129.84 (plus $132.02 when the check clears)

I have future plans to fill it back up, but I’m not going to do anything at the moment, just continue staying the course for now.

Hope everyone has a fantastic week!