:::: MENU ::::

Cashback Savings

by

I mentioned a couple of times that my only credit card offers cashback rewards. And I have it set up to deposit the rewards into a standalone savings account every time those rewards reach $20.

As I have been working through my plans and budgets, I took a look at how those rewards added up this year.
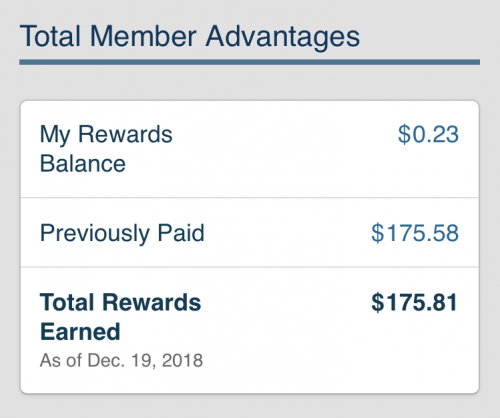

Not too shabby for a little bit of passive income. I’m not designating it towards anything at this point, just pretty much ignoring it and hoping to be surprised as it grows.

I am also continuing to save my loose change and $5 bills. Gymnast pulled the $5 out a couple of months ago and counted it. It was $120 at the time. But I’ve left it alone since then.

I realize this blog is not about saving, and I am focused on my debt. But these gimmicky savings plans just give me a small piece of added security.

Do you have a passive savings source? Or an account that you just let grow unsupervised?

Hope’s Winter 2019 Budget

by

I have settled on a Winter budget. I anticipate sticking to this budget for the first quarter of the new year.

I really appreciate your comments and suggestions when I posted my first draft. And I really considered them all.

Without further ado, here is my budget for the beginning of 2019.

Hope's Winter 2019 Monthly Budget

DescriptionMonthly Budget
Rent$650
Groceries$600
Household (hygiene, cleaning, etc.)$10
Auto - Gas$120
Health Insurancemedicaid ($305)
Auto/Rent Insurance$100
Utilities (gas, electric, water, trash)$290
Life Insurance$23 (paid quarterly)
Buffer
Kids Activities$50
Entertainment/Clothing$150
Auto - Maintenance/Fees$30
Debt Payments - minimum payments
Car Payment$400
Collections #2$246
Credit Card$0
Collections #3$0
Student Loans$100
Total Personal$2,769

Things to Note

  1. I’ve cut my personal hygiene budget after reviewing my numbers from this past year.
  2. I left my Kids’ Activities and Entertainment and Clothing budgets as they were. I looked at the numbers, what is coming for us all in this coming year and feel they are reasonable.
  3. I cut the Auto Maintenance numbers after reviewing this past year, and with continued hopes that my car will hold up with minimal expenses this next year.
  4. I removed the budgeted money toward my credit card debt as I continue to use it as a revolving line of credit.
  5. BIGGEST CHANGE – I have decided NOT to payoff  the tax debt (Collections #2) this month. Instead, I am adding that $1,000 to my existing EF, bringing the total to $2,000. This means, I will have to continue to pay the $246 for 4 months (unless I have a fantastic month during the first quarter.)
  6. Finally, I am going to pay a $100 towards my student loan debt. It just doesn’t make sense to me to be decreasing all my debts, but this one grows by $70+ per month. It seems counter-productive.

Hopes

My hope is that as my business continues to grow in the new year, I can stick to this budget and pour any additional income to paying off my debts. But worse case, I will have Collections #2 paid off before my full payments for my student loans kick in. And will hopefully, also have Collections #3 settled and paid.

So my debt priorities as we start the new year are as follows:

  1. Grow EF by $1,000 – done
  2. Pay off Collections #2 – no later than April, possibly sooner.
  3. Pay off Collection #3 – as soon as Collections #2 is closed out.
  4. Credit Card.
  5. Car.
  6. Student Loans.