:::: MENU ::::

Debt Update & Automating Payments on my Student Loan

by

I have decided to automate my debt payments. Maybe automate isn’t the right way to say it…

For my student loan, which requires a minimum monthly payment of $307, I have decided to pay $100 per week. By breaking down the payment every week, it helps me get ahead a little bit at a time, saves on interest, I think, and at the end of month all my bills are paid and there are no large payments. (Well, except rent, and I think it would irritate my landlord to receive weekly payments.)

I guess this is still a bit muddled still in my head. But I’ve decided to give it a try…

I’ve scheduled $100 to go towards my student loan every Saturday. My pay hits for my work through Upwork on Thursdays. Therefore, I have a couple of days to make any changes if the need should arise. But by the end of the first month, I should be almost an hundred dollars ahead. And I’m assuming they will be putting it all toward principle, but I’m going to have to watch to see how it goes.

$100 per week x 52 weeks = $5,200 towards my student loans

Student Loan: Current balance is $33,779

That’s definitely not gazelle fast on pay off, but definitely more than the minimum and when I have several months of abundant workload, I can put some extra toward it.

I’m planning on doing the same thing with my car loan…but I’m thinking of doing $250 per week on it. I have to finish my new budget to see if this is sustainable for me though. But I won’t start it until the new year.

$250 x 52 weeks in the year = $13,000 towards the car.

Car Loan: Current balance is $19,492

That’s not too shabby. I am definitely slowly digging myself out of this mess.
Toy figure of a man shoveling coins


Why I Had to Pay Off My Debt Twice

by

I spent nearly three years paying off a pile of debt while I wrote for BAD. How long did it take me to jump back in? Six months. Within two years, I racked up $70,000.

Some of you asked what on earth started the downhill slide. A stupid car. My car started dying at stop lights. I was pregnant with my second baby and I was certain someone would crash into my car and kill all three of us. Did I have my car checked to see how much it would be to fix it? Um. Does the oil change guy count? No? Then, uh, no. I didn’t have the car diagnosed. I drove to a dealership and traded it in for a beautiful, expensive, brand new SUV. I cried while signing the SEVEN YEAR loan papers and cried the entire ride home. I knew I made a mess.

Did I stop there? Did I scream, ‘Enough is enough!’?!?! Oh no friends, that would have been responsible. And we all can clearly see I wasn’t exactly responsible at that time. I dusted off my trusty credit card and charged away to the tune of $15,000 over a two year period. We added on some legal debt (we live in California, it’s practically required!), medical debt, and a sprinkling of student loans.

Why? I forgot the reason I wanted to get rid of our debt.

If your ‘why’ isn’t strong enough, your resolve to stay out of debt won’t be either.

In 2014, my brother told me about YNAB, a budgeting app that was working really well for his family. I mentioned to my husband that I wanted to give it a shot and, being the awesome supportive rock star that he is, he sat down and told me we should start immediately.

Over the next three years, we scrimped, we saved, we pushed, we cried (OK, only I cried but that’s not important), and we finished… again. We had enough to pay off the debt in January 2017 but I was pregnant at the time and we decided to hold all payments but the minimum until after the baby was born as instructed by Dave Ramsey. I thought this suggestion was ridiculous…until an emergency C-section and a NICU stay changed my mind. But that’s a story for another day.

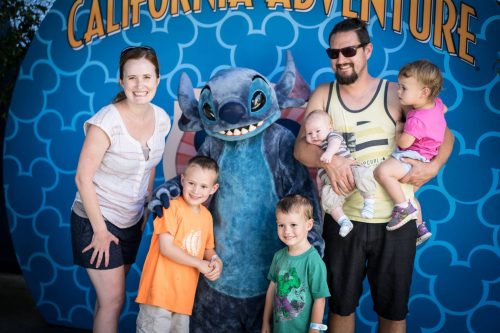
In April 2017, we wrote the last check. We saved cash to take the kids to Disneyland to celebrate. I cried that whole trip. For once, I wasn’t crying because I made a mess… I was crying because I cleaned it up.

Family of six posing with Stitch at Disney California Adventure

Two months ago, my husband became a full-time stay at home dad. We have had our eyes on that prize for more than two years. That’s my ‘why’…and it’s AWESOME.

Now you’re caught up. Where do we go from here? We’re looking at the big daddy of debts to tackle…our mortgage.

Three hundred and twenty thousand dollars. We live in So Cal. Our mortgage is laughable to locals but to us, it’s simply not something we want to live with anymore.

Dear Bank of America…

We’re coming after you.